Selling Your West Maui Home: What It's Worth, What It Costs, and How It Actually Goes

Every West Maui sale comes down to three questions: what will the property actually sell for, what will the sale cost you, and what has to happen between "let's list it" and the wire hitting your account. This page answers all three the way I answer them for my own sellers — with real numbers and no varnish — as a REALTOR® Broker and Global Luxury Specialist with Coldwell Banker Island Properties in Kapalua. Whether you're selling an oceanfront estate, a Kapalua villa, or a Kaanapali condo you've rented for years, the framework is the same. What's changed in 2026 is the market you're selling into, and for condo owners, the zoning underneath the property.

What is the Maui market actually doing right now?


Buyers have the leverage, and pricing is doing all the work.

In August 2026, Maui County closed 64 single-family homes at a median price of $1,200,000 — down 7.9% from August 2025 — with a median 128 days on market. Condos closed 68 sales at a median of $564,950, down 13.1% year over year, with a median 171 days on market.

The more useful signal is underneath those medians: unit sales are rising while prices fall. Condo closings were up 19.3% year over year, and pending condo sales were up 54.9%. Buyers are transacting again — at a price. Very little sells at list, and a price adjustment is a normal feature of this market rather than proof that a listing is broken.

Two caveats before you apply any of that to your own property. These are countywide figures, and West Maui is its own market — Kapalua, Kaanapali, Napili, and Honokowai each behave differently, and so do individual buildings. And the condo medians blend two increasingly different products: apartment-zoned units affected by the vacation rental phase-out, and hotel- or resort-zoned units that aren't. Zoning is now a pricing input, not a footnote.

Source: REALTORS® Association of Maui, August 2026 closed-sales report, as reported by Maui Now, Sept. 4, 2026. Figures are Maui County-wide. Ask me for the current numbers for your specific building or neighborhood.

What is my West Maui home actually worth?

Not what Zillow says, and not what your neighbor got in 2021. The honest answer comes from a Comparative Market Analysis (CMA): a data-driven opinion of what your property will likely appraise for, what it will likely sell for, and where the listing price should sit. Mine are built from MLS data, tax records, public records, current market trends, and something no algorithm has — building-level and street-level knowledge. In West Maui, two units in the same complex can carry very different values depending on floor, orientation, and view; two homes on the same ridge can differ by whether they catch the trade winds.

A CMA is not an appraisal. An appraisal is a formal, licensed valuation your buyer's lender will order later. The CMA is what we use to make the pricing decision — and that decision does more work than anything else in the sale.

One more thing that matters more in 2026 than it did in 2021: I price off actual recorded sale prices, not list prices. In a market where most closings land below asking, comps built on list prices will talk you into a number the market won't pay.

Home Valuation

Why is the listing price the highest-stakes decision in the sale?


Because your listing gets one debut, and the market reads the price before it reads a word of the description.

Set it high "to leave room to negotiate" and the buyers who would have paid market value may never tour it — they're shopping a bracket below. The property sits, and when the reduction eventually comes, it arrives with a question mark attached: buyers wonder what's wrong. Set it low and you invite a different suspicion, and you may hand away money you can't recover.

That penalty is heavier right now than it has been in years. With condos running a median of 171 days on market countywide and buyers holding options, an overpriced debut doesn't cost you a few weeks — it can cost you a selling season, and the reductions you make chasing the market usually total more than the discount you were trying to avoid.

Priced at real market value, a property does what well-priced West Maui listings do: draws the buyers actually shopping that bracket, generates competing interest, and sells on a timeline you control instead of one the market imposes on you. Accurate pricing isn't caution — it's the aggressive move.

I own a condo. Does the vacation rental phase-out affect what I can sell?

If your unit is in an apartment-zoned building on the Minatoya List, yes — and buyers are pricing it in, so you need to know exactly where your building stands before you set a number.

The short version of where things stand as of September 2026:

  • Ordinance 5909 (Bill 9), signed December 15, 2025, phases out transient vacation rental use in apartment districts (A-1 and A-2), including Minatoya List units. Short-term rental use ends January 1, 2029, in the West Maui Community Plan area and January 1, 2031, in the rest of Maui County.

  • Ordinance 6008 (Bill 88), effective June 22, 2026, created two new hotel zoning districts, H-3 and H-4, as a pathway for affected properties to keep operating as vacation rentals — but only if a specific property is actually rezoned.
  • The County Council is handling that rezoning building by building, through numbered resolutions moving in waves. A resolution referring a property to the Maui Planning Commission is not a rezoning — the land designation only changes when the Council passes the final map-amendment ordinance for that specific property. Which wave a building sits in, and how far along it is, changes month to month.

  • Hotel- and resort-zoned properties are not part of the apartment-district phase-out. Long-term rental use also remains available in apartment districts.
  • Lawsuits challenging the phase-out are pending. As of this update, no court order has paused the deadlines.

What this means for a seller is practical, not political. Your building's zoning and its rezoning status are now among the first things a serious buyer's agent checks, and they move value. Before we price, we confirm the current status for your specific property, we document it accurately, and we disclose it. I track where every Minatoya List property sits at mauicondorentalrules.com and update it as the Council moves.

This is a fast-moving public process, and nothing here is legal advice. Confirm your property's current zoning and rezoning status with the Maui County Planning Department, and talk to your own attorney or CPA about how the timeline affects your plans.

Do I have to disclose sea level rise?

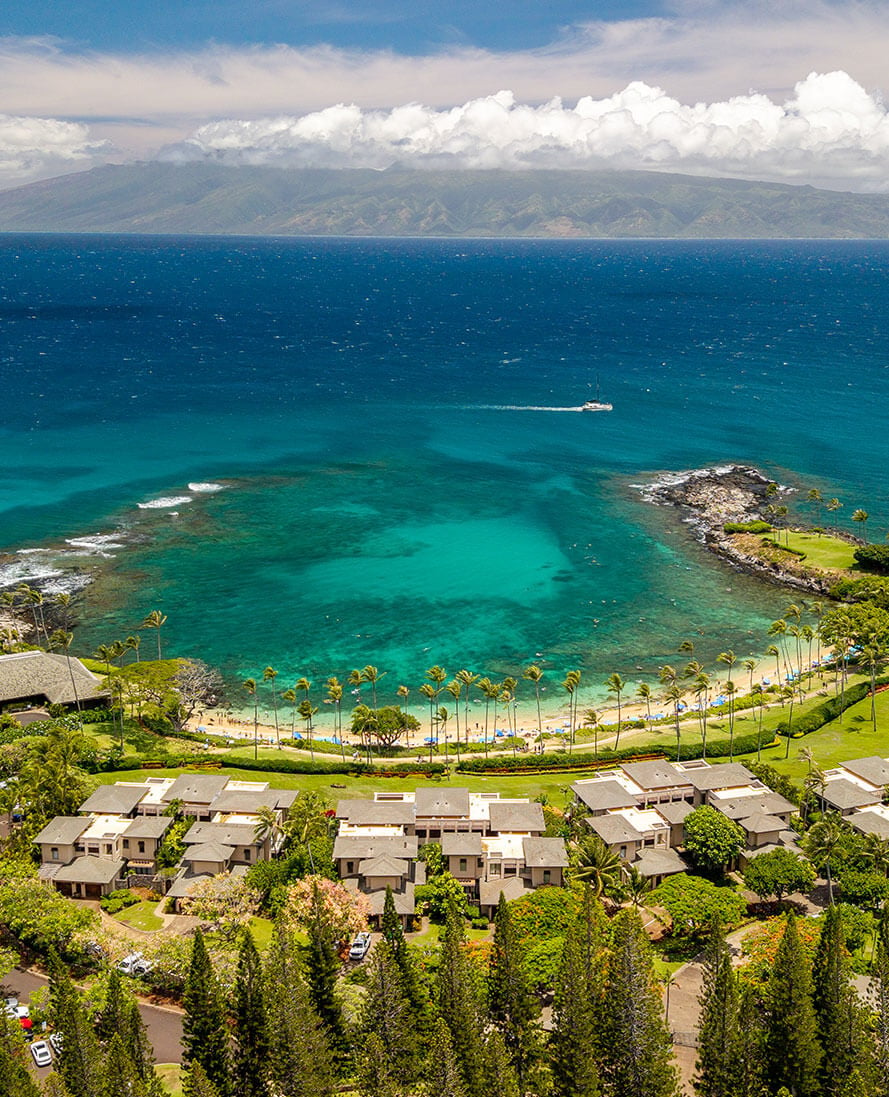
If any part of the property sits in the State's 3.2-foot Sea Level Rise Exposure Area, yes — Hawaii law (HRS §508D-15, as amended in 2021) makes it a mandatory seller disclosure, and it appears on the standard Seller's Real Property Disclosure Statement. The State's Sea Level Rise Viewer maps it by tax map key.

For oceanfront and near-shore West Maui property, treat this as a pricing and marketing question as well as a legal one. Buyers now look it up themselves, insurance underwriting reflects it, and the County has used the same exposure mapping as a criterion in the hotel rezoning resolutions. Sellers who get in front of it — accurate disclosure, documentation ready, questions answered before they're asked — lose fewer deals in escrow than sellers who let a buyer discover it in week three.

When should I list?

Market conditions matter more than the calendar, but both count. Before we pick a date, I'll show you what's currently listed in your building or neighborhood (your actual competition), what's sold recently and how long it took, and what seasonal buyer traffic looks like for your property type — mainland second-home buyers shop on a different rhythm than local move-up buyers. With inventory where it is, the competition question is doing more work than the season question: three similar units already sitting in your building matters more than the month on the calendar. Timing the debut well is free money; it costs nothing but patience and planning.

What should I do to the property before it goes to market — and what should I skip?

Sellers routinely over-invest in the wrong things and under-invest in the right ones. I walk every listing and split the punch list three ways:

Worth doing, almost always

  • Fix anything a home inspector would flag — better to handle it now than negotiate it under deadline pressure in escrow.
  • Declutter and depersonalize, so buyers see the property, not your life in it.
  • Deep-clean, and refresh paint where it's tired.
  • Curb appeal — the first impression starts at the driveway or the lobby.

Worth discussing, case by case

  • Upgrades and renovations. Some return more than they cost in this market; many don't — and in a buyer's market, fewer do. I'll tell you which is which for your specific property before you spend a dollar.
  • Professional staging, where the property and price point warrant it.

Non-negotiable

  • Professional photography. Most buyers meet your property on a screen before they ever smell the plumeria — the photos are the first showing.
  • Pets out for showings, lights on, property show-ready every time.
Kapalua

How will buyers actually find the property?

A West Maui listing has three audiences — mainland and international second-home buyers, local buyers, and the agents who represent both — and the marketing has to reach all three:

  • The story first. What sets the property apart, what the neighborhood or building offers, and why this one over the three others like it — written before any ad runs, because it drives everything else.
  • Photography and video built around the property's best light and angles.
  • MLS syndication to the portals buyers actually search.
  • Targeted digital and social campaigns aimed at the buyer profile for your specific property, not a generic audience.
  • Global luxury reach — the Coldwell Banker Global Luxury® network through Coldwell Banker Island Properties, which puts West Maui property in front of luxury buyers and their agents worldwide.
  • Showings with feedback loops. Every showing produces intelligence: what buyers responded to, what they hesitated on, what's worth adjusting. You'll hear all of it — on the communication schedule you choose, not mine. In a market this selective, showing feedback is your earliest and most honest pricing signal.

What happens when offers come in?


This is where the sale is actually won. Price is only one term — closing date, contingencies, inspection handling, and the buyer's financing strength all move the real outcome. My job is to read the whole offer, know the players where possible, and negotiate the package that nets you the most with the least risk of the deal cracking in escrow. Sometimes the best offer isn't the biggest number; it's the one that closes.

Expect a negotiation. In today's market, offers at or above list are the exception, and buyers are coming in with inspection expectations and credit requests attached. That's not an insult; it's the current market's opening move. What matters is what you net and whether the deal survives to recording.

What does selling actually cost me at closing?

Closing costs split between buyer and seller by category, and some line items are negotiable as part of the offer. The typical allocation under the standard Hawaii Association of REALTORS® Purchase Contract:

Closing costBuyerSeller
Standard title insurance premium40%60%
Extended coverage policy (ALTA / Lender's Policy)X
Drafting mortgage, note, or agreement of saleX
Drafting conveyance documents & bills of saleX
Buyer's consentsX
Seller's consents (e.g., lessor's consent)X
Buyer's notary feesX
Seller's notary feesX
Escrow fee50%50%
Recording fees (except clearing seller's title)X
Recording fees to clear seller's title (e.g. mortgage release)X
Required staking or surveyX
Condo/association ownership transfer feesX
FHA/VA discount points and mortgage feesX
Conveyance tax (graduated by price and buyer's declared use)X
FIRPTA withholding (if applicable)X
HARPTA withholding (if applicable)X

(Source: Hawaii Association of REALTORS® Standard Form Purchase Contract, via Fidelity National Title. Typical example, not a guarantee — confirm your actual costs with your escrow officer.)

Two seller line items worth understanding before you see them on a settlement statement:

  • Hawaii conveyance tax — paid by the seller and graduated by sale price and by whether the buyer will occupy the property. On resort-area second-home and investment purchases the higher tiers apply, and at West Maui price points this is a meaningful line rather than a rounding error. Ask escrow for your exact figure when we build your net sheet.

  • Brokerage compensation — compensation is negotiable and is agreed in writing between you and your brokerage in the listing agreement, and separately with any buyer's brokerage. I'll walk you through the options and what each one does to your net before you sign anything.

Before you list, I'll prepare a seller's net sheet — your realistic walk-away number after every cost on this table, so there are no surprises at the closing table.

I'm a non-resident, or I'm selling a rental. What withholding applies to me?

Two laws matter here, and both are prepayments toward possible capital gains tax — not penalties:

HARPTA (Hawaii) — the buyer is generally required to withhold 7.25% of the amount realized when the seller is not a Hawaii resident, remitted to the Hawaii Department of Taxation within the required deadline after closing, unless an exemption applies. A properly structured 1031 exchange may qualify. If the withholding would far exceed your actual Hawaii tax, you can apply for a reduction or waiver on Form N-288B before closing, or claim an early refund on
Form N-288C after.

FIRPTA (federal) — withholding is generally 15% of the amount realized when the seller is a foreign person. Reduced rates of 10% or 0% apply only in limited residential cases tied to the sale price and the buyer's certified intent to use the property as a residence. A withholding certificate (Form 8288-B) can reduce the amount, but IRS processing takes months — start early.

What happens between contract and closing?

Escrow opens, and the clock starts on a sequence of deadlines: buyer's inspections, document deliveries, contingency removals, the buyer's loan progress. I manage that calendar so nothing slips, and you get regular updates without having to chase anyone. Your side of the countdown, as closing approaches:

  • Documents reviewed and signed on schedule
  • Forwarding address set; bank, insurance, and property-tied subscriptions notified
  • Appliance manuals and warranties gathered for the buyer
  • Professional cleaning booked for after move-out
  • Utilities scheduled to transfer on closing day — not before
  • Your own final sweep: cabinets, drawers, closets, garage, storage
  • Homeowner's insurance canceled or updated only after the new deed records
  • Keys, garage openers, and remotes left on the counter; lights off, doors locked

What if I need somewhere to go next?


Selling is half the move. If you're staying on Maui, we start the buying conversation in parallel so you're not timing two transactions blind — see my Condo Buying Guide and Single-Family Home Buying Guide. If you're headed off-island, I'll connect you with a strong agent in your next market through the Coldwell Banker Island Properties referral network, and I stay your Maui resource after the sale — including the annual market check-in I do with all my past clients.
Key takeaways

  • This is a buyer's market. Countywide condo medians are down 13.1% year over year with a median 171 days on market, while sales volume climbs — buyers are active, but only at the right price.
  • The listing price is the highest-leverage decision in the sale — your debut happens once, and the market reads the price first.
  • If you own an apartment-zoned condo, confirm your building's Bill 9 and rezoning status before you price. Zoning is now a value driver, and buyers check it first.
  • Prep spending should be surgical: inspection-level fixes, decluttering, and photography almost always pay; many renovations don't. Get the punch list before you spend.
  • Ask for a seller's net sheet before you list — your walk-away number after the closing-cost table above, not the sale price, is the number that matters.
  • Non-residents: HARPTA (7.25%) and possibly FIRPTA apply unless you qualify for an exemption — a 1031 exchange among them. Handle the paperwork early.
  • The best offer is the one that closes on your terms, not always the biggest number.

Separator line

Frequently Asked Questions

A REALTOR®-prepared Comparative Market Analysis (CMA), built from MLS data, recorded sale prices, tax records, and local knowledge of your specific building or neighborhood. It's not an appraisal, but it's the most accurate estimate available before you list.

It's a buyer's market, not a closed market. In August 2026, Maui County condo sales were up 19.3% year over year and pending sales up 54.9%, while the median condo price fell 13.1% to $564,950 and homes sold at a median of $1,200,000. Property is selling — accurately priced property. Whether it's the right time for you depends on your net, your timeline, and, for apartment-zoned condos, the phase-out clock.

It applies to apartment-zoned (A-1 and A-2) properties on the Minatoya List. Under Ordinance 5909, vacation rental use in those districts ends January 1, 2029 in West Maui and January 1, 2031 elsewhere in Maui County. Ordinance 6008 created H-3 and H-4 hotel districts as a rezoning pathway, and the Council is working through properties resolution by resolution. Hotel- and resort-zoned properties are not part of the apartment-district phase-out. Confirm your specific property's status with the County before making a decision.

An appraisal is a formal, licensed valuation typically ordered by the buyer's lender during escrow. A CMA is a REALTOR®'s market-based opinion of value, used to set the listing price before you go to market.

Anything a home inspector would flag, first — handling it now beats negotiating it under deadline pressure later. Then decluttering, deep cleaning, paint where needed, and curb appeal. Ask which upgrades actually return their cost before spending on renovations; many don't.

A line-by-line estimate of what you'll actually walk away with after closing costs, withholding, payoffs, and brokerage compensation — prepared before you list, so the decision is made on real numbers.

Both. Costs split by category under the standard Hawaii Association of REALTORS® contract, and some items are negotiable between the parties. See the full table above.

HARPTA requires the buyer to withhold 7.25% of the amount realized when the seller is not a Hawaii resident, unless an exemption applies. It's a prepayment toward capital gains tax you may owe, not an extra tax, and it can be reduced or waived in advance on Form N-288B.

Yes, if any portion of the property falls within the State's 3.2-foot Sea Level Rise Exposure Area. Hawaii law makes it a mandatory seller disclosure, and it's on the standard Seller's Real Property Disclosure Statement.

A properly structured 1031 exchange defers the capital gains tax and may qualify for a HARPTA exemption. The requirements and strict timeline are on my 1031 Exchange & Investor Guidelines page. Confirm your situation with your CPA.

It depends on price accuracy, condition, zoning, and current inventory in your building or neighborhood. Countywide medians in August 2026 were 128 days for homes and 171 days for condos — but before we set expectations, I'll show you actual days-on-market for recent sales of properties like yours.

No. Nearly everything runs by email and e-signature. Off-island and international sellers should expect the final closing documents may require in-person notarization where you are.

Market conditions outweigh the calendar, but buyer traffic does have seasonal rhythm — and it differs for second-home buyers versus local buyers. The honest answer depends on your property type and building; ask for the current picture rather than a rule of thumb.

Ready When You Are

Are You Ready For A Straight Answer?

Share the property, plan, or question you are working through.

I will tell you what I see, what needs closer verification, and what I would consider before moving forward. You do not need to have every detail figured out before we speak.

Book A CONSULT
Call 808-250-1163
Keri Nicholson